Got a Bonus? Jio IPO or SIP: A Simple Decision Framework
Your bonus has just landed. On the same day, every headline is talking about the Jio Platforms IPO. Put it all in the IPO, start a SIP, or split it? Here's a calm way to decide.
October brings two things at once for many IT professionals: festive or variable-pay bonuses, and the biggest IPO news in years. The timing makes the IPO feel like the obvious place for the money.
This post is not about whether Jio Platforms is a good company. It is about where your bonus goes, and in what order. No stock tip. Just a framework.
Jio Platforms IPO: The Facts So Far
Last updated: 15 October 2026. Based on public reports after the RHP filing. Confirm every detail from the RHP before applying.
| Item | Detail (as reported) |
|---|---|
| RHP filed | 14 October 2026 |
| Price band | ₹1,065 – ₹1,119 per share |
| Anchor bidding | 19 October 2026 |
| Subscription window | 21 – 23 October 2026 |
| Basis of allotment | 26 October 2026 |
| Listing (tentative) | 28 October 2026, NSE and BSE |
| Issue type | Fresh issue of up to 27 crore shares |
| Issue size (upper band) | About ₹30,213 crore |
| Lot size | Reports differ — check the RHP |
| Special categories | Reported RIL shareholder and employee reservations |
Jio Platforms operates across telecom, broadband, cloud, AI and enterprise services. How the money raised will be used is set out in the RHP's "Objects of the Issue" section.
This post does not discuss valuation, grey market premium or listing-day expectations. Those are not the decision this post is about.
IPO vs SIP Is Not a Like-for-Like Choice
People ask "IPO or SIP?" as if the two were rival products. They are not.
- An IPO is an event. A one-time bid for shares of one company. Allotment is uncertain. The listing price can be above or below the issue price.
- A SIP is a habit. A fixed amount invested regularly in a diversified mutual fund, linked to a goal, building units over years.
| Feature | IPO application | SIP |
|---|---|---|
| What you own | Shares of one company | Units of a diversified fund |
| Frequency | One-time | Recurring |
| Certainty of deployment | Uncertain (allotment may not happen) | Invested on each SIP date |
| Typical horizon | Varies by investor | Multi-year, goal-linked |
| Effort | Read RHP, bid, track allotment | Set up once, review yearly |
| Main risk | Single-company and listing-price risk | Market risk across the portfolio |
Comparing them head-to-head is the wrong question. The better question is: which slice of my bonus has which job?
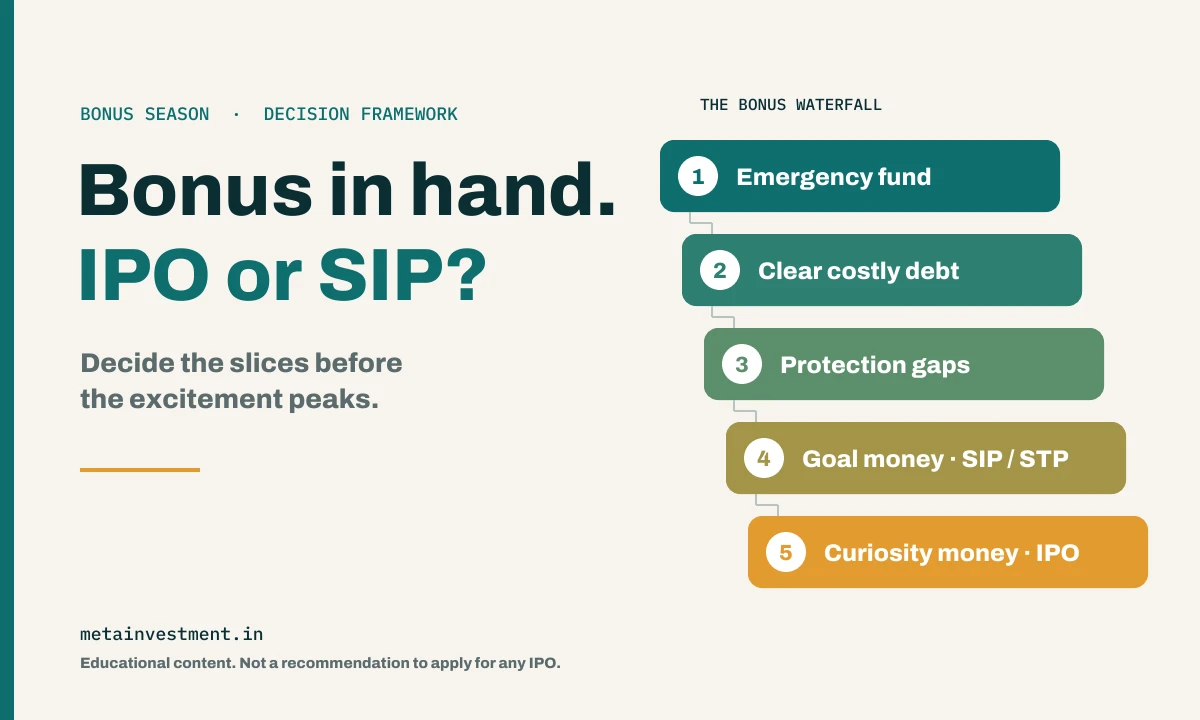
The Bonus Waterfall: Decide in This Order
This is the core of the framework. Money flows down only after each step above it is filled. Read it as a checklist.
- Emergency fund first. Is there a reserve of roughly 6 months or more of essential expenses in something liquid? With IT hiring flat and layoffs in the news, this step protects every other step. The Layoff Runway Calculator can help size it.
- Clear costly debt. Credit card balances, personal loans and BNPL dues usually cost far more than most investments can reliably earn. Paying them down is a known benefit.
- Close protection gaps. Is there term cover independent of the job? Is there personal health cover beyond the employer policy, which ends on the last working day?
- Fund goal money. House down payment, child's education, retirement. Long-horizon goals are where SIPs, STPs and NPS usually come in.
- Satellite or "curiosity" money. Only now consider a small, pre-decided slice for opportunities like IPOs, sized so that losing part or all of it would not hurt any goal.
An illustrative example
Hypothetical, for illustration only — not a recommended allocation.
Rohan, 32, a software engineer in Pune, receives a ₹3 lakh post-tax bonus. His emergency fund is already in place and he has no card debt. His health cover is only through his employer.
- He tops up a personal health policy first.
- He sends a large part to his long-term goals through an STP into equity funds.
- He keeps a small slice — an amount he is comfortable losing — for an IPO application.
Rohan's split reflects his situation. Someone with card debt, or no emergency fund, would arrive at a very different split. The suitability of any investment category depends on an investor's financial goals, risk appetite, investment horizon and overall financial circumstances.
If You Are Considering the IPO Slice: Know These First
- Retail limit: a retail individual investor can apply for up to ₹2 lakh. Above that, the application moves to the non-institutional category.
- One PAN, one application: multiple applications under the same PAN in a category can be rejected.
- Money is blocked, not debited: under ASBA or a UPI mandate, the amount stays in your account but is frozen until allotment. Check your UPI app's IPO mandate limit before the window opens.
- Allotment is uncertain: when the retail portion is oversubscribed, allotment is usually by lottery. Big, popular issues often see very heavy demand.
- Read the RHP: especially Risk Factors and Objects of the Issue. It is long, but it is the real document.
- Don't fund it with borrowed or earmarked money: breaking an FD meant for a goal, pausing a goal SIP, or taking a loan to apply turns a curiosity bet into a goal risk.
Tax basics
The bonus is already taxed as salary. Gains on IPO shares are taxed separately:
- Sold within 12 months: short-term capital gains, generally at 20%.
- Held over 12 months: long-term gains above ₹1.25 lakh a year, generally at 12.5%.
- Surcharge and cess apply on top.
Tax rules change and individual situations differ, so confirm the current position with a qualified tax professional.
If You Are Taking the SIP Route With a Lump Sum
A bonus is a lump sum. A SIP is monthly. Three common ways to bridge the gap:
- Lump sum: invest the whole amount at once in the chosen fund category.
- STP (Systematic Transfer Plan): park the money in a liquid or similar fund, then transfer a fixed amount into an equity fund every week or month. This spreads entry across market levels. It does not assure a better outcome.
- Step-up SIP: if an increment has come with the bonus, this is a good moment to raise the monthly SIP itself. The Step-up SIP page explains how it works, and the SIP Calculator can help model contributions.
Whichever route, tie each rupee back to a named goal from Step 4. Money with a job is harder to spend by accident.
Common Bonus Mistakes IT Professionals Make
- Chasing the headline with the entire bonus. One stock, one event, all the money.
- Letting lifestyle absorb it. Without a plan, a bonus usually disappears within a month or two.
- Ignoring ESOP or RSU concentration. If a large part of your wealth is already in your employer's stock, adding more single-stock exposure deepens the concentration. The 8 Freedoms Checklist covers this.
- Treating an IPO as a sure quick gain. Listing prices can go either way.
- Deciding after the excitement peaks. The slices are easier to decide calmly, before the subscription window opens.
A Note for NRIs
NRIs working abroad in IT can generally apply in Indian IPOs through ASBA-enabled NRE (repatriable) or NRO (non-repatriable) accounts linked to an eligible demat account, subject to the offer document's terms. Repatriation rules and tax in both countries matter. A dedicated NRI follow-up post will cover this in detail; meanwhile, the NRI Corner covers the broader options.
How Meta Investment Can Help
We offer two separate services. They are kept apart on purpose.
1. Bonus and goal planning conversation Working out the waterfall for your own situation — emergency fund, protection, goals, SIP, STP and NPS. If investments are made through a mutual fund distributor, the distributor may receive commissions from Asset Management Companies. Such commissions should not influence suitability-based recommendations.
2. IPO application facilitation Help with the application process through our partner broking firm. Meta Investment receives a fee from broking firm for each IPO application facilitated. We do not recommend whether to apply for any IPO.
📞 WhatsApp: 9309806281 | 📧 info@metainvestment.in
Key Takeaways
- An IPO is a one-time event; a SIP is a long-term habit. They do different jobs.
- Decide your bonus in order: emergency fund, costly debt, protection, goals, then curiosity money.
- IPO money is blocked, not debited, and allotment is uncertain for retail investors.
- Never fund an IPO bid by breaking goal money or borrowing.
- Lump sum, STP and step-up SIP are three ways to put a bonus to work for long-term goals.
- Confirm all IPO details from the RHP and tax treatment with a qualified professional.
The Window Closes in Days. Your Goals Run for Decades.
The Jio Platforms IPO window is three days long. Your child's education, your home and your retirement run for decades. Decide the slices before the excitement peaks, and let each rupee know its job.
If you are working out where this year's bonus should sit, that is a conversation worth having.
Interested in Investing? Connect with Meta Investment
Meta Investment is a financial product distribution and services firm. If you'd like to explore whether a financial product is the right fit for your portfolio, our team will walk you through the details, help you assess suitability, and guide you through the onboarding process.
Mutual Fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. This post is for educational purposes only and is not a recommendation to subscribe, or not to subscribe, to any IPO. IPO details are based on public reports as of 15 October 2026; please refer to the RHP. Tushar Paturde is an AMFI-registered Mutual Fund Distributor (ARN-129322) and a CFP® professional, and is not a SEBI-registered Investment Adviser or Research Analyst. Tax treatment depends on individual circumstances and prevailing law; please consult a qualified tax professional.
Meta Investment – Your Investment and Insurance Companion
Frequently Asked Questions
Should I put my bonus in the Jio IPO or in SIPs?
There is no single answer, because an IPO and a SIP do different jobs. An IPO application is a one-time bid for shares of one company, while a SIP is a recurring, diversified investment linked to long-term goals. Many people work through a sequence first — emergency fund, high-cost debt, insurance gaps, goal money — and only then decide whether a small, pre-decided slice goes to opportunities like IPOs.
What is the price band and date of the Jio Platforms IPO?
As per reports following the red herring prospectus filed on October 14, 2026, the Jio Platforms IPO has a price band of ₹1,065 to ₹1,119 per share. It is scheduled to open on October 21 and close on October 23, 2026, with allotment expected on October 26 and listing on October 28. Final details should be confirmed from the RHP.
Can I apply for an IPO and continue my SIPs?
Yes. An IPO application and a running SIP are independent of each other. The IPO amount is blocked in your bank account through ASBA or a UPI mandate, so the only practical check is that your account has enough balance for both the blocked IPO amount and the upcoming SIP debits.
What happens to my money if I don't get an IPO allotment?
Under the ASBA process, the application money is only blocked in your bank account, not debited. If you do not receive an allotment, the block is released after the basis of allotment is finalised. If you receive a partial allotment, only the amount for the allotted shares is debited.
Why is IPO allotment uncertain for retail investors?
When the retail portion of an IPO is oversubscribed, shares are typically allotted by a computerised lottery, with the aim of giving at least one minimum lot to as many applicants as possible. Large, widely tracked issues can see heavy oversubscription, so an application does not ensure an allotment.
What is the maximum a retail investor can apply for in an IPO?
A retail individual investor can apply for up to ₹2 lakh in a mainboard IPO. Applications above ₹2 lakh fall in the non-institutional investor category. Only one application per PAN is valid in a category, and multiple applications under the same PAN can be rejected.
Is it better to invest a bonus as a lump sum or through STP?
Both are ways of deploying the same money. A lump sum invests everything at once, while a Systematic Transfer Plan parks the amount in a liquid or similar fund and moves a fixed sum into an equity fund at regular intervals. STP spreads entry across market levels; neither approach assures a better outcome, and the choice depends on comfort with volatility and the goal's horizon.
How much of my bonus should go into IPOs?
There is no universal percentage. A common planning approach is to first cover an emergency fund, repay costly debt, close insurance gaps and fund goal-linked investments. Any amount directed to IPOs after that is usually sized so that losing part or all of it would not affect any important goal.
Can I use my bonus to increase my SIP permanently?
A bonus is a one-time amount, so it does not by itself fund a higher monthly SIP. However, a bonus often arrives alongside an increment, and many investors use that moment to register a higher SIP or a step-up SIP. Part of the bonus can also serve as a buffer that keeps a higher SIP comfortable during a tight month.
Should I break an FD or stop my SIP to apply for an IPO?
Planning discussions generally advise against funding an IPO application by breaking fixed deposits meant for other goals, stopping goal-linked SIPs or borrowing. An IPO allotment is uncertain and listing price can be above or below the issue price, so the money used is usually money not earmarked for anything else.
How are gains from IPO shares taxed in India?
IPO shares become listed equity shares after listing. If sold within 12 months, gains are generally short-term capital gains taxed at 20%; if held longer than 12 months, long-term gains above ₹1.25 lakh in a financial year are generally taxed at 12.5%, plus applicable surcharge and cess. Tax rules can change, so confirm the current position with a qualified tax professional.
Is the bonus itself taxed before I invest it?
Yes. A performance or festive bonus is part of salary income and is taxed at your applicable slab, usually through TDS deducted by the employer. The amount you invest is therefore post-tax money, and any gains from investing it are taxed separately under capital gains rules.
Can NRIs apply for the Jio Platforms IPO?
NRIs can generally apply in Indian IPOs through ASBA-enabled NRE (repatriable) or NRO (non-repatriable) bank accounts linked to an eligible demat account, subject to the terms in the offer document. The applicable category, repatriation rules and tax treatment should be checked before applying.
What should I read before applying for any IPO?
The red herring prospectus (RHP) is the primary document. Its Risk Factors, Objects of the Issue and financial information sections explain what the company does, how the money raised will be used and what could go wrong. Headlines and grey market chatter are not a substitute for the RHP.
What is the difference between an IPO and a SIP?
An IPO is an event: a one-time chance to bid for shares of a single company at a set price band, with uncertain allotment. A SIP is a habit: a fixed amount invested regularly in a diversified mutual fund, building units over time through rupee cost averaging. One is a single-stock bid; the other is a long-term, goal-linked process.


म्युच्युअल फंड अपडेट्स, SIP टिप्स आणि बाजारात काय घडतंय. रोजचा गोंधळ नाही — फक्त वाचण्यासारखं काही असेल तेव्हाच.
Read more about
- Welcome to Meta Investment blogFunds
- EMI vs SIP
- Taxation on Liquid Funds - Updated for Finance Bill 2023 (Budget 2023)
- Running, SIP and Coaching!
- A Comprehensive Guide to Save Tax with Insurance in India
- All About AIFs (Alternative Investment Funds)
- Lucrative Investment Opportunities Options for NRIs in India
- PMS in India: A Guide to Portfolio Management Services
- The Power of Chai, SIP, and Building Long-Term Wealth
- Using Capital Gains Bonds in India to Maximizing Wealth Growth
- The Tax Harvesting Garden - Cultivating Wealth with Care
- Invest in this Nifty 50 Index Fund to Save Tax
- From Appathon to SIPathon
- Building Your Crorepati Dream
- Unveiling the Secrets of Wealth
- The Cafe vs. The Nest Egg
- A Fresh Perspective on Portfolio Management Services (PMS) for NRI/HNI Investors
- This Mother's Day, Give the Gift of Security: Invest for Her Future and Protect Her Health
- Don't Be a Target: Investor Awareness and ARN Verification to avoid Mutual Fund fraud
- Strava and SIPs: How One Cyclist Conquered Both Roads and Finances
- Don't Panic Sell!
- Growing Their Future: Why Mutual Funds Are a Smart Investment for Minors
- Abans Global Arbitrage Fund: A Deep Dive
- How To Lose 1 Crore Rupees
- Boost Your Retirement Savings with Enhanced NPS Benefits in Budget 2024
- Taxation- Capital Gains- Revised Rates vs Previous Rate
- The Gift That Keeps on Giving
- Equity Linked Savings Schemes
- Navigating The Current Equity Market Correction
- Pre-Budget Portfolio Tune-Up: 3 Things to Consider Now
- 7-Day Plan for Indian Women to Kickstart Their Financial Journey: From Scarcity to Abundance
- How to Become an Accredited Investor in India: A Guide for HNIs | SEBI Framework
- Wishing You a Prosperous Gudi Padwa, Ugadi, Cheiraoba, Navreh, and Cheti Chand!
- Master Market Volatility: Krishan Sharma’s Investing Wisdom
- Estate Planning in India: Wills, Trusts & Tax Tips for NRIs & Residents
- Mutual Will: Why Married Couples Must Have One | Estate Planning Guide
- Understanding Beneficial Nominee in Insurance & Its Role in Estate Planning
- NRI Mutual Fund Taxation: How DTAA Can Save You Tax (Anushka Shah Case)
- Gold vs. Mutual Funds vs. Multi-Asset Funds: Best Investment for Akshaya Tritiya 2025
- Mirae Asset Global Allocation Fund - Invest in Global Markets via GIFT City | Tax Benefits for NRIs & HNIs
- HDFC Life Click 2 Achieve – Guaranteed Savings Plan with Life Cover
- The Power of a No-Contest Clause: How Ratan Tata's Will Prevented a Legal Battle
- India Surpasses Japan to Become 4th Largest Economy in 2025 | Growth & Challenges
- 📈💰 World Emoji Day Special: Smart Investing, SIP & Wealth Growth Made Fun! 🚀💡
- RBI’s August 2025 MPC Meeting: Key Highlights & What It Means for You
- ManipalCigna Sarvah Uttam Health Insurance Plan: Comprehensive Coverage with Unique Benefits
- Mutual Funds Are the New Status Symbol (Not Your Bank Balance)
- Mutual Fund Scheme Name Changes in India (2025) – Complete List & Reasons
- From Freedom Fighters to Financial Freedom: Gen Z Investing & Independence Day Lessons
- All Weather Gold: A Principal-Protected Way to Bet on Gold (Until Aug 31)
- ESAF SFB NCD Issue: 11.30% Coupon | Basel II Compliant Bonds
- Begin Your Wealth Journey This Ganesh Chaturthi: Ganpati-Inspired Mutual Fund Lessons
- Tata AIA Health SIP Review 2025: A Smart Health + Investment Plan?
- NPCI Raises UPI Transaction Limits: A Complete Guide to High-Value Payments from Sept 2025
- India’s First Specialized Investment Fund (SIF): Bridge Between MF & PMS | quant Guide
- New GST Changes 2025: Impact on Investors, Sectors, and Mutual Fund Opportunities
- Beyond the Market Rollercoaster: A Guide to the Altiva Hybrid Long-Short SIF | Edelweiss MF
- Diviniti Equity Long Short Fund NFO 2025 | Investment for Indian HNIs & NRIs
- The Investor and The Distributor: A Lesson on SIP Discipline
- Financial Wellness for Men: Boost Health with Smart Investing, SIP & Retirement Planning
- Kotak Market Outlook 2026: India Equity, Debt, Gold & Silver
- SEBI Equity Fund Rules 2026: Multi Cap, Flexi Cap Changes
- SEBI Debt Fund Rules 2026: Debt Funds Masterclass - Duration, Credit Risk, Yields Guide
- ICICI Pru Thematic Advantage Fund: What the Recategorization Means for You
- Marcellus Global Equities Fund NFO: Invest in Global Markets via GIFT City
- NPS Swasthya Explained: Wait for the Health-Linked Pension, or Buy Health Cover Now?
- AMFI Stock Reclassification: What It Means for Your Fund
- FTSE India Index Explained: What It Is & Why It Matters Now
- US Fed Holds Rates: What It Means for Gold, Silver & the Rupee
- Tata Mumbai Marathon 2027 Fee Is ₹5,000: How to Budget for It
- Pune on India's Wealth Map: What the 2026 List Reveals
- Closing Auction Session: Why Arbitrage Fund NAVs Jumped
- Emergency Fund: The Money That Buys the Right to Say No
- The 8 Freedoms Checklist for Financial Independence
- SEBI's Proposed MF-Only PMS: What Investors Should Know
- How to Check an Insurer's Complaint Record Before You Buy
- Your Increment Came Through. Did Your SIP?
- PFRDA's New NPS Scheme Categories: What Actually Changed
- SEBI Mandatory Nomination Rules for Demat and MF Folios
- Financial Green Flags That Matter More Than Salary
- Record SIP Inflows in a Falling Month: Reading August's AMFI Data
- UPI Charges Above ₹2,000: What Changes on October 15
- Fed Rate Hike 2026: What It Means for Indian MF Investors
- Alchemy India Long Term Fund: GIFT City Guide for NRIs
- Navratri to Diwali 2026: Your Festive-Season Money Calendar
- NPS Sanchay Explained: Who It Is For and How It Differs
- RBI Hikes Repo Rate to 5.50%: What It Means for Your EMI and FD
- Got a Bonus? Jio IPO or SIP: A Simple Decision Framework
- म्युच्युअल फंड: अल्पवयीन मुलांसाठी स्मार्ट गुंतवणूक का आहे?
- महिलांसाठी आर्थिक यशस्वीतेची 7-दिवसीय नियोजन: टंचाईपासून विपुलतेकडे
- तुम्हाला गुढी पाडवा, उगादी, चेइराओबा, नवरेह आणि चेटीचंदच्या हार्दिक शुभेच्छा!
- बाजारातील चढ-उतारांवर मात करा: कृष्ण शर्मा यांच्याकडून महत्त्वाचे धडे
- भारतात एस्टेट प्लॅनिंग: NRI आणि रहिवाशांसाठी इच्छापत्र, ट्रस्ट आणि कर टिप्स
- म्युच्युअल विलः विवाहित जोडप्यांसाठी का आवश्यक? | एस्टेट प्लॅनिंग मार्गदर्शक
- विमा योजनांमध्ये लाभार्थी नामनिर्देशित व्यक्ती (बेनिफिशियरी नॉमिनी) आणि एस्टेट प्लॅनिंगमधील त्याची भूमिका
- NRI म्युच्युअल फंड कर: DTAA मदतीने कसे कर बचत करू शकता (अनुष्का शहा केस)
- सोने vs म्युच्युअल फंड vs मल्टी-अॅसेट फंड: अक्षय तृतीया २०२५ साठी सर्वोत्तम गुंतवणूक
- मिराए अॅसेट ग्लोबल अलोकेशन फंड - गिफ्ट सिटी मार्गे जागतिक बाजारात गुंतवणूक | एनआरआय आणि एचएनआय साठी कर फायदे
- HDFC Life Click 2 Achieve – निश्चित बचत योजना आणि जीवन विमा संरक्षण
- स्काय वन कॉर्पोरेट पार्क: HNIs आणि NRIs साठी एक उत्तम गुंतवणूक संधी
- 📈💰 वर्ल्ड इमोजी डे स्पेशल: SIP आणि गुंतवणूक मजेशीर पद्धतीने! 🚀💡
- RBI चा ऑगस्ट 2025 MPC बैठक: प्रमुख हायलाइट्स आणि तुमच्यासाठी काय अर्थ आहे
- एप्रिल २०२५ पासून भारतातील म्युच्युअल फंड स्कीमच्या नावातील बदल - संपूर्ण यादी आणि कारणे
- Demat आणि MF Folio साठी SEBI चे अनिवार्य Nomination नियम
- पगारापेक्षा जास्त महत्त्वाची असणारी आर्थिक हिरवी निशाणे
- ₹2,000 वरील UPI शुल्क: 15 ऑक्टोबरपासून काय बदलते
- नवरात्री ते दिवाळी 2026: सणासुदीच्या काळातील आर्थिक दिनदर्शिका
- NPS Sanchay सोप्या भाषेत: कोणासाठी आणि इतर NPS पेक्षा वेगळे कसे
- RBI ने रेपो दर 5.50% केला: तुमच्या EMI आणि FD वर काय परिणाम?
Related Posts
This communication is intended solely for general educational and informational purposes. The information provided is general in nature and does not take into account the specific financial goals, risk profile, investment horizon, financial circumstances or other requirements of any particular investor. It should not be construed as personalised investment advice or as a recommendation to buy, sell or hold any specific financial product.
International investments may carry currency/exchange-rate, foreign-market, geopolitical, taxation, regulatory, remittance and liquidity risks.
Distributor Disclosure: Where this content is provided by a distributor/intermediary, any applicable commission, remuneration, affiliation or other material conflict of interest shall be disclosed separately. The availability of a product through the distributor does not by itself imply that the product is suitable for every investor.
No Guarantee: No statement on this page should be interpreted as a promise, assurance or guarantee of returns or investment outcomes.
Meta Investment – Your Investment and Insurance Companion